M/s Shakti Industries vs. Directorate General of GST Intelligence, Lucknow & Others
GST Adjudication Order Set Aside for Violation of Natural Justice
Allahabad High Court | Judgment: 19 August 2026⚖️ Court & Bench
| Court | Allahabad High Court |
| Judge | Justice Saumitra Dayal Singh |
| Judge | Justice Swarupama Chaturvedi |
📋 Case Information
| Case No. | Writ Tax No. 2810 of 2026 |
| Judgment Date | 19 August 2026 |
| Petitioner | M/s Shakti Industries |
| Respondents | Directorate General of GST Intelligence, Lucknow & 2 Others |
🔎 Issue Before the Court
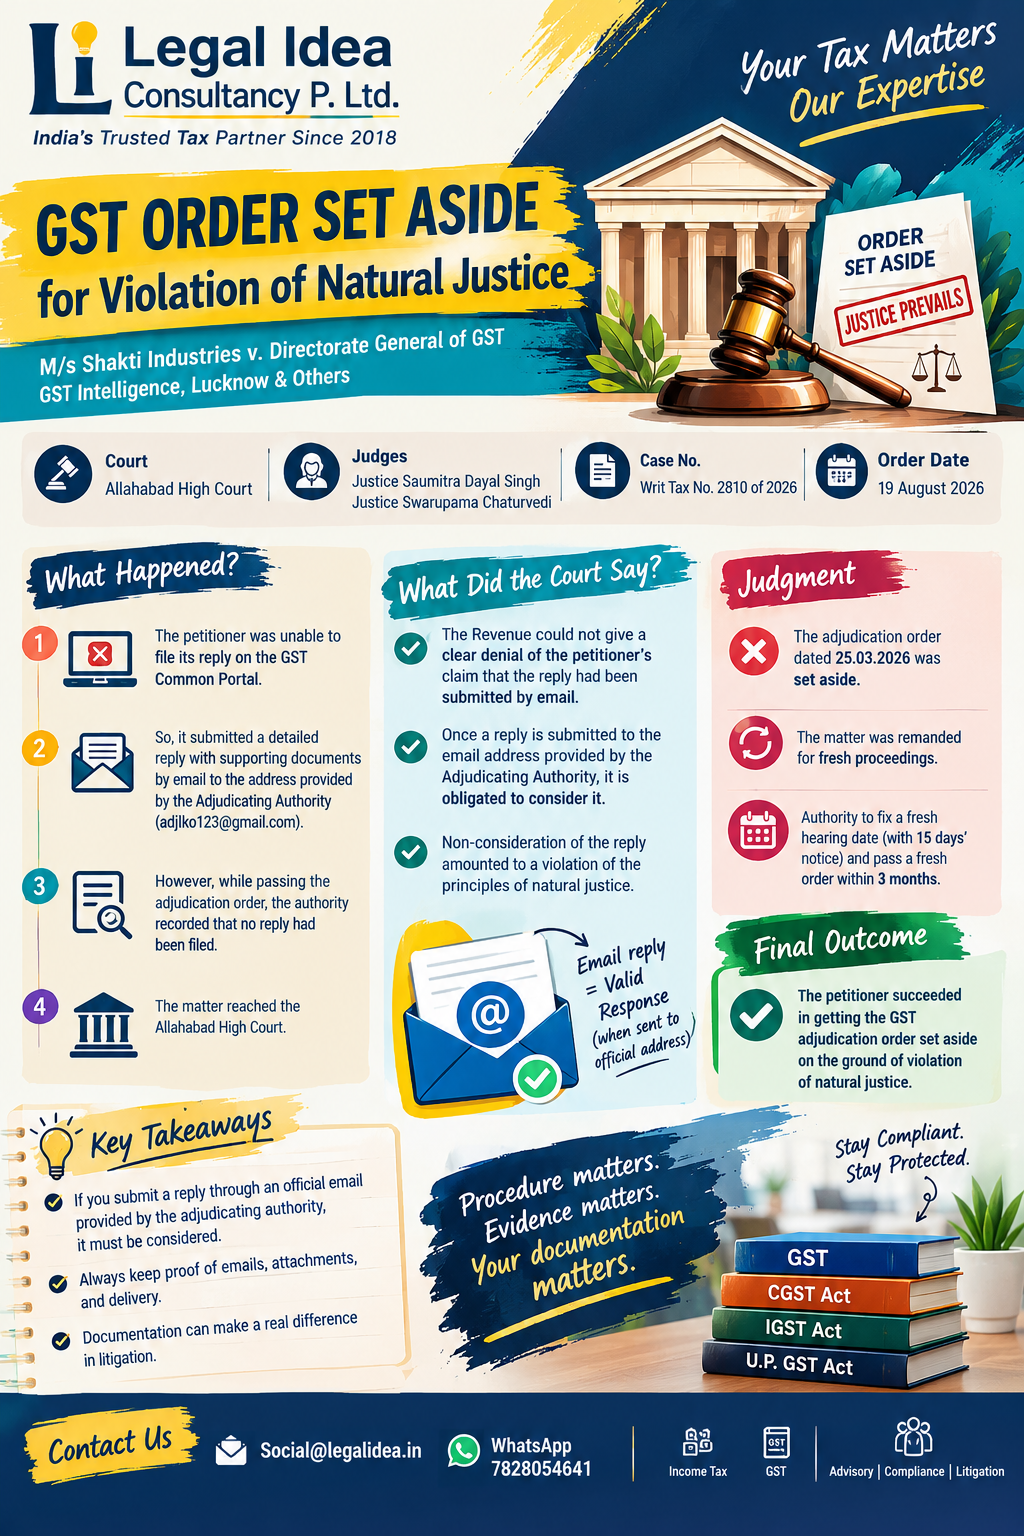
The petitioner challenged the common adjudication order dated 25.03.2026, passed under Section 74 of the CGST Act, 2017, read with the U.P. GST Act, 2017 and IGST Act, 2017.
The proceedings related to Financial Years 2019-20, 2020-21, 2021-22, 2022-23 and 2023-24 (January).
The petitioner claimed that it was unable to file its reply on the GST Common Portal and therefore submitted its detailed reply and supporting documents by e-mail.
📧 Submission of Reply by E-mail
According to the petitioner, its detailed reply along with supporting documents was submitted by e-mail on 06.03.2026.
The reply was sent to the e-mail address specifically provided by the Adjudicating Authority:
However, while passing the adjudication order, the authority recorded that no written submission or reply had been filed by the petitioner and other firms.
🏛️ Court's Findings
The High Court noted that the Revenue's counsel had not received any clear denial of the petitioner's factual assertion regarding submission of the reply by e-mail.
The Court held that once the petitioner had submitted its reply to the e-mail address provided by the Adjudicating Authority, the authority was obligated to consider that reply.
Non-consideration of a reply duly submitted by the taxpayer amounted to a violation of the principles of natural justice.
📜 Judgment & Directions
The Allahabad High Court found a fundamental procedural defect in the adjudication proceedings.
Accordingly, the impugned adjudication order dated 25.03.2026 was set aside in respect of the petitioners involved in the batch of petitions.
The matter was remanded for fresh proceedings:
- The Adjudicating Authority shall fix a fresh date of hearing with at least 15 days' advance notice.
- The petitioner shall cooperate in the proceedings and shall not seek undue or lengthy adjournments.
- After hearing the petitioner, the authority may pass a fresh final order, preferably within three months.
✅ Final Outcome
The petitioner succeeded in getting the GST adjudication order dated 25.03.2026 set aside on the ground of violation of natural justice.
Importantly, the High Court did not finally decide the underlying tax dispute on merits. The matter was sent back to the GST authority for fresh proceedings after providing a proper opportunity of hearing and considering the petitioner's reply.
💡 Key Tax Takeaway
Non-consideration of a duly submitted reply can constitute a violation of the principles of natural justice and may result in the adjudication order being set aside.
Legal Idea Consultancy P. Ltd.
Comments
1